
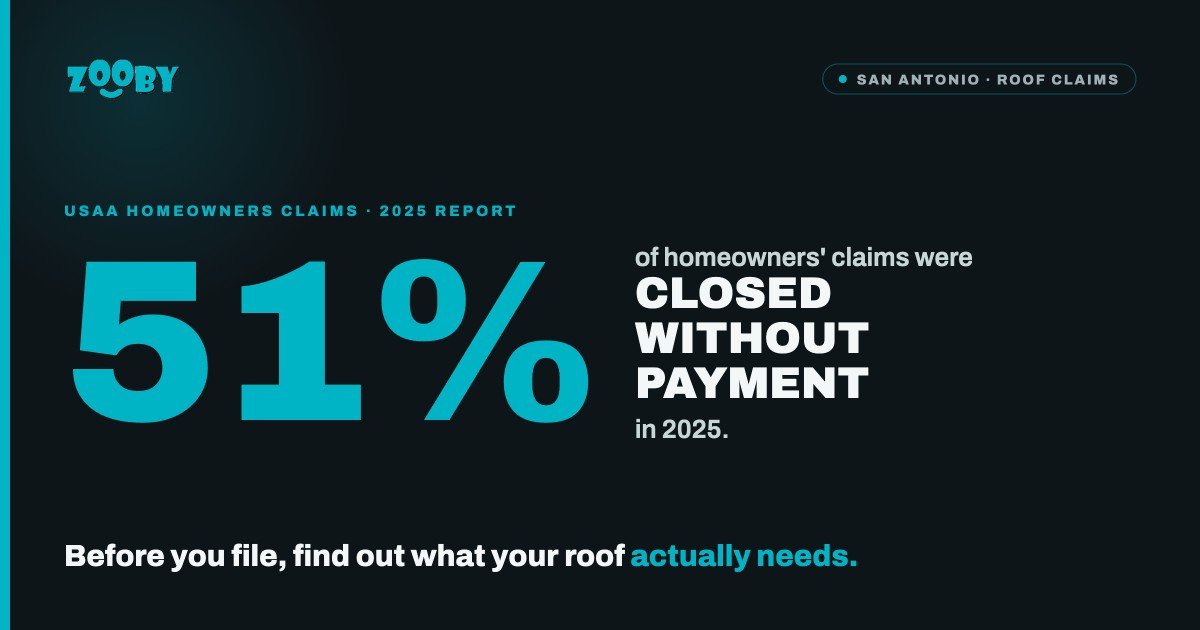
Recent reporting found that approximately 51% of homeowners' claims handled by USAA and affiliated insurers closed without payment in 2025. Zooby Home Exteriors explains the distinction and its practical effect on homeowners in a new article. The figures arrive as hail damage receives renewed national attention, with a July 2026 New York Times report examining the growing cost of hail.
For San Antonio homeowners, the two stories point to the same concern: storm damage can become a household financial problem, especially when repair costs approach or fall below a percentage-based wind or hail deductible. Zooby is encouraging homeowners to understand the roof condition, the likely repair cost, and the deductible before automatically filing a claim.
After a hailstorm, homeowners may notice loose shingles, granules in the gutters, damaged vents, ceiling stains, or signs of roofing damage throughout the neighborhood. Those signs deserve attention, but they do not reveal the roof's full condition. A professional inspection can help identify visible hail or wind damage, lifted or missing shingles, granule loss, damaged flashing, cracked pipe boots, water intrusion, age-related deterioration, and isolated problems that may be repairable.
Many Texas homeowners policies use percentage-based wind and hail deductibles. For a home insured for $350,000, a 2% wind or hail deductible equals $7,000. If an insurance carrier approves $6,500 in covered roof repairs, the homeowner may receive no payment because the approved amount is lower than the $7,000 deductible. The Texas Department of Insurance provides a similar example in its consumer guidance.
Hail is one of the most expensive severe weather threats in the United States. The Insurance Institute for Business & Home Safety reports that annual hail losses routinely exceed $10 billion. Zooby is encouraging San Antonio homeowners to calculate their wind and hail deductible in dollars before storm damage creates pressure to act quickly.
Some homeowners assume storm damage means the entire roof must be replaced, but limited damage may be corrected by replacing damaged shingles, repairing flashing, or completing another targeted roof repair. Other roofs may have widespread storm damage that makes roof replacement the responsible option.
Zooby recommends that homeowners review the wind and hail deductible, replacement cost or actual cash value terms, roof age limitations, depreciation requirements, cosmetic damage exclusions, and any wind or hail exclusions. Homeowners should ask their insurance agent or carrier to explain how those terms apply to their policy.
Zooby is not advising homeowners to avoid legitimate insurance claims. Serious storm damage, active leaks, and conditions that could cause further property damage should be addressed promptly. However, filing a claim may affect premiums or claim-free discounts, as noted by the Texas Department of Insurance.
After inspection, the appropriate option may be repair, Zoobification, or full roof replacement. Zoobification is Zooby's service for qualifying asphalt shingle roofs that are aging but still have useful life. Zooby also provides a Limited Credit Warranty for Zoobification; if complete roof replacement later becomes necessary, Zooby may apply a credit toward a full roof replacement performed by Zooby, subject to the written warranty terms.
Zooby reminds homeowners that a Texas roofing contractor cannot legally waive, absorb, rebate, or help a homeowner avoid paying an insurance deductible. The Texas Department of Insurance warns consumers that deductible-waiver offers may involve rebates, inflated invoices, or other arrangements intended to make the deductible disappear.